Lincoln Funding Group Inc
Mortgage brokerage in downtown Livermore for Tri-Valley purchases and refinances.
About
South Livermore Avenue is the main street of downtown Livermore, and number 39, suite 201, is an upstairs office a block from the First Street shops and the Bankhead Theater. Lincoln Funding Group Inc works from there as a mortgage brokerage; Steve Rodriguez is a manager. Public records also show an earlier Dublin address for the firm, so this page, compiled from directory data without the owner's review, should be confirmed by phone.
Mortgages and home loans
A mortgage broker arranges loans between borrowers and wholesale lenders rather than lending its own money. For Livermore buyers that means purchase mortgages on Tri-Valley homes, refinances when rates move, cash-out loans for remodels, and often FHA, VA and jumbo programmes that a single bank may not carry. Brokers of this kind also handle investment-property loans and, in some firms, real estate sales alongside the financing.
The value of a broker is the comparison: several lenders' pricing on the same file, and someone whose job is to get an awkward file, such as self-employment income, approved.
Preparing to apply
Ask for the broker's NMLS identifier and the company's, and look both up on the NMLS Consumer Access site, which shows licence history and any actions. Ask how the broker is paid, whether by the lender or by you, and get a loan estimate in writing before committing. Bring two years of tax returns, recent pay stubs and bank statements, and a note of any credit issues so they can be addressed early. Ask how long pre-approval takes and which lenders the firm actually places most of its loans with.
Livermore, the Tri-Valley and Tracy
The downtown Livermore office serves Pleasanton, Dublin, San Ramon and Danville, Sunol to the west, Fremont over the hills, and Tracy on the far side of the Altamont, where many Livermore buyers now look.
Reach the office on 925-398-8466. The chamber invites the owners to claim this listing and bring it up to date.
Services
Typical for this type of businessFinancing for buyers of homes in Livermore and the Tri-Valley, with the broker comparing several wholesale lenders on the same application and handling the file to closing.
Rate-and-term refinances when market rates fall, and cash-out refinances that turn home equity into funds for a remodel, debt consolidation or an ADU.
Government-backed programmes for first-time buyers and veterans, with lower down payments and specific property and appraisal rules that a broker walks through.
Mortgages above the conforming limit, which most Tri-Valley purchases exceed, placed with lenders whose jumbo terms suit the borrower's income profile.
Financing for rental houses and small multi-unit properties, where lenders look at rental income and reserves as well as the borrower's own earnings.
Details
Location and service area
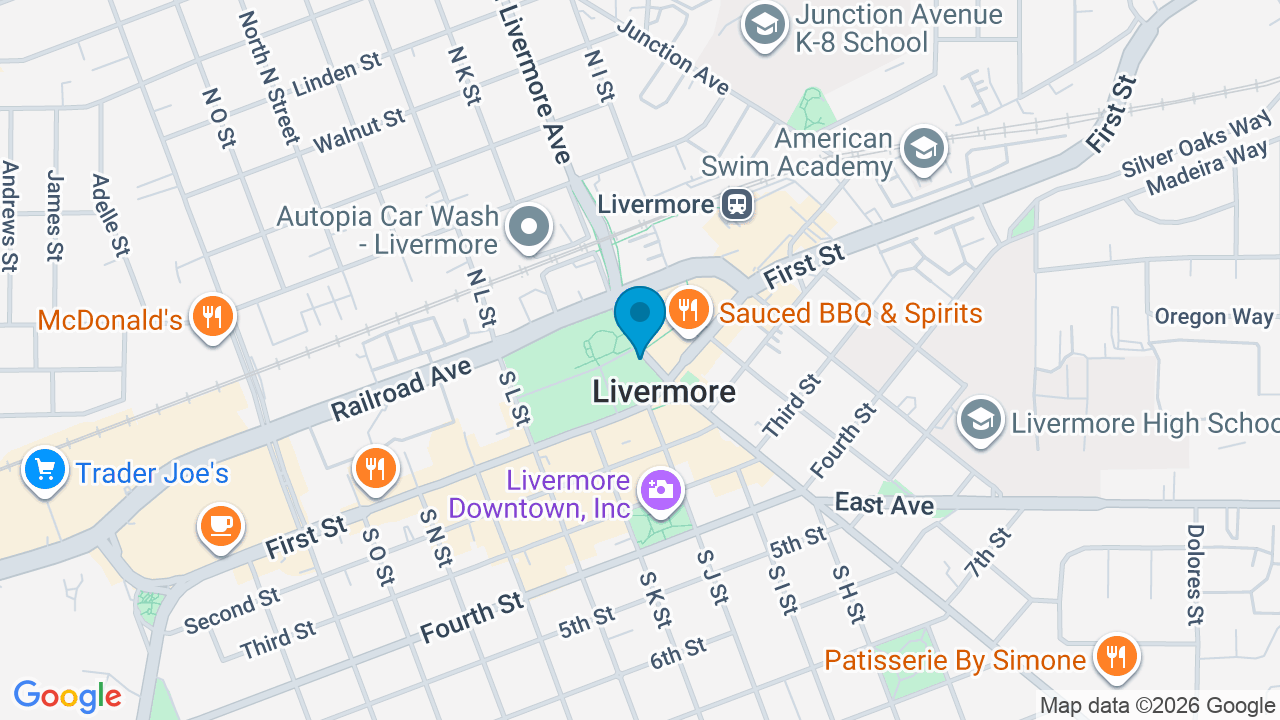
Livermore, CA 94550-3119
Common questions
Typical for this type of businessWhat does a mortgage broker do that a bank does not?
A broker shops your application to several wholesale lenders and compares their pricing and rules; a bank offers only its own products. Brokers are paid by the lender or the borrower, so ask which applies and get the loan estimate in writing.
How do I verify a mortgage broker's licence?
Ask for the individual's and the company's NMLS identifier and enter them on the NMLS Consumer Access website, which shows licence status, history and any regulatory actions. California brokers also hold a state real estate or finance licence.
What documents do I need for pre-approval?
Typically two years of tax returns and W-2s, recent pay stubs, two months of bank statements, photo identification and permission for a credit check. Self-employed borrowers should add profit-and-loss statements and business returns.
Before you hire
- Look up the broker and the company on NMLS Consumer Access before sharing documents.
- Ask how the broker is compensated and get a loan estimate in writing.
- Ask which lenders the firm places most loans with and why.
- Confirm the office address by phone, since records show more than one over the years.
- Compare the estimate with at least one other lender before locking a rate.
Resumen en español
En el centro de Livermore, en South Livermore Avenue, Lincoln Funding Group Inc trabaja como corredor hipotecario: gestiona préstamos de compra y refinanciación con varios prestamistas mayoristas en lugar de prestar su propio dinero, incluidos programas FHA, VA y jumbo. Steve Rodriguez figura como gerente. Antes de solicitar, pida el número NMLS del corredor y de la empresa, pregunte cómo se le paga y obtenga una estimación del préstamo por escrito. Atiende Pleasanton, Dublin, San Ramon, Danville y Tracy. Esta ficha se compiló con datos de directorios y espera la revisión del dueño. Llame al 925-398-8466.
Compiled from public business records held by the San Francisco Bay Area Hispanic Chamber of Commerce. Sections marked as typical describe what a business of this kind usually offers, not what this business has confirmed.
Own this business? Confirm or correct this listing →